
Executive Summary
Ollie’s Bargain Outlet Holdings Inc (OLLI) operates a specialized retail model as a primary liquidation and closeout channel for brand-name consumer goods. The company generates revenue by purchasing excess inventory, discontinued product lines, and packaging changeover stocks from a network of over 1,200 manufacturers and wholesalers at a fraction of the wholesale cost and passes the savings to customers.
The quality of its economics is characterized by an industry-leading gross margin profile near 40% and a robust operating margin exceeding 11%, underpinned by a “buy cheap, sell cheap” philosophy that transfers significant value to the consumer while maintaining high internal capital efficiency.
The core competitive edge resides in a deeply entrenched, long-tenured merchant team and a scaled distribution infrastructure that allows the company to act as a preferred liquidity provider for major global brands.
Conversely, the primary risk is the structural reliance on the physical retail format in an increasingly digital landscape and the potential for a “deal drought” if manufacturing supply chains become hyper-efficient.
Ollie’s is a high-growth, counter-cyclical extreme-value retailer that leverages deep manufacturer relationships to provide a unique “treasure hunt” experience, delivering a Return on Invested Capital (ROIC) significantly above its cost of capital through scaled opportunistic procurement.
1. What They Sell and Who Buys
Ollie’s focuses on a highly fluid and opportunistic product assortment, which is fundamentally distinct from the predictable, planogram-driven inventory of traditional big-box retailers. The company’s merchandise is categorized primarily by its origin as closeout stock, which allows for extreme discounts ranging from 20% to 70% below traditional retail prices.
Core Product Categories and Inventory Dynamics
The inventory is divided into four major pillars, each serving a distinct strategic purpose in driving store traffic and maintaining margins:
Consumables (36.2% of sales): This category is the engine of repeat foot traffic. It includes food, health and beauty aids, and household chemicals. Unlike other segments, consumables are characterized by a higher frequency of purchases. By offering recognized national brands like Clorox, Tide, or Kellogg’s at extreme discounts, Ollie’s ensures that customers return frequently, even if they do not find a specific “treasure hunt” item in other aisles.
Home Products (29.2% of sales): This segment covers housewares, bed and bath textiles, floor coverings, and small appliances. This category often benefits from department store overstocks and packaging changes. For example, if a major textile brand changes its thread-count labeling or color palette, Ollie’s acquires the “old” stock at significant discounts, allowing it to sell premium linens at prices comparable to entry-level goods elsewhere.
Seasonal Items (14.3% of sales): This category includes toys, patio furniture, garden supplies, and holiday décor. Seasonal items are highly cyclical and represent a significant portion of the “treasure hunt” allure. The company’s ability to buy toys and holiday items out-of-season or from bankrupt retailers (such as the recent acquisition of inventory from failed toy chains) provides a unique margin expansion opportunity during the fourth quarter.
Other Products (20.3% of sales): This includes books, stationery, electronics, hardware, and sporting goods. The book department is particularly notable, as Ollie’s is one of the largest closeout retailers of hardcover books in the United States, often selling $25-30 titles for $3.99 to $5.99.
Customer Profile and Market Segmentation
The target customer is broadly defined as “anyone age 25 or older with a wallet or a purse” who is seeking value.
However, institutional data suggests a more nuanced profile. The Ollie’s customer is typically a middle-income shopper who is increasingly brand-conscious but budget-constrained.
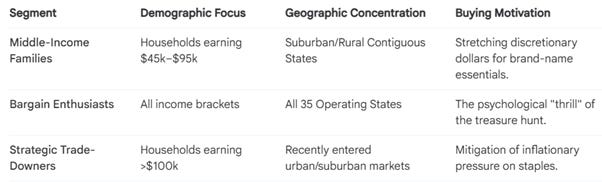
The primary pain point solved is the “inflation tax” on brand-name goods. While dollar stores offer low absolute price points (often by reducing package sizes), Ollie’s offers full-sized national brand products at a lower unit cost.
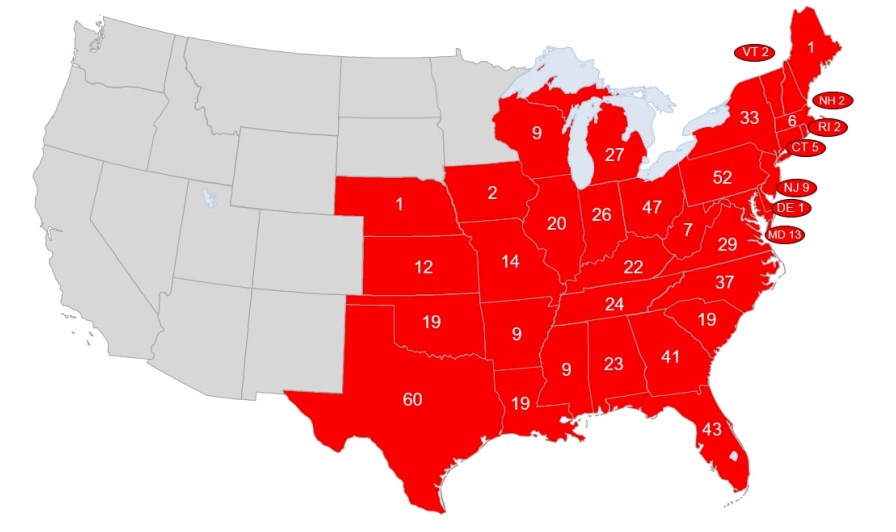
The company’s contiguous expansion strategy into 35 states as of June 2026 ensures that it captures “abandoned” customers from bankrupt peers like Big Lots and 99 Cents Only, filling a vacuum in the extreme-value landscape.
2. Revenue Model
Ollie’s employs a procurement-centric revenue model where value is captured through the “buy” rather than the “sell”. The company operates on the principle that the profit is made when the item is purchased from the vendor, which then dictates the competitive retail price.
Pricing Mechanism and Value Capture
To understand Ollie’s pricing, one must move away from traditional retail “cost-plus” models. Ollie’s utilizes Asymmetric Arbitrage: they decouple the price they pay from the price they charge, anchoring the price entirely to the Manufacturer’s Suggested Retail Price of the original brand. Every price tag at Ollie’s prominently features the “Their Price” (the price at department or specialty stores).
By maintaining a strict discipline of pricing at 20% to 70% below that anchor, Ollie’s captures the “consumer surplus” - the psychological value a customer feels when they get a $100 brand for $30-40.
Unlike Walmart ot Target, which negotiate for a 2% lower wholesale price on a permanent item, Ollie’s merchants look for inventory distress.
Ollie’s captures value by acting as an insurance policy for manufacturers. When a major brand (like P&G) has 500,000 units of a detergent with an old label, that inventory is a liability.
Ollie’s captures value by offering “total clearance”. They take the entire lot, pay cash immediately, and promise not to advertise the brand in a way that cannibalizes the manufacturer’s full-price sales.
In exchange for this “problem-solving” service, manufacturers sell to Ollie’s at prices often below the cost of raw materials.
Revenue Structure and Segments
The revenue is 100% transactional and derived from physical store locations. There is no recurring subscription revenue (unlike warehouse clubs), and the company currently generates zero revenue from e-commerce.
Revenue and Valuation Comparison
Key Revenue Drivers
New Store Unit Growth: Revenue is primarily a function of the store count. With 672 stores as of Q1 FY2026 and a long-term target of 1,300+, the company’s primary revenue level is the physical expansion of its footprint.
Comparable Store Sales (Comps): Comps are driven by a mix of transaction count (foot traffic) and basket size (average spend per visit). In Q4 FY2025, a 3.6% increase in comps was driven by both metrics, indicating that existing customers are visiting more often and buying more per trip.
Deal Size and Quality: The availability of “mega-deals” - defined as large-scale liquidations of national brands - can cause quarterly revenue spikes. For instance, the modification of the toy category and increased investment in seasonal decor were cited as “big wins” that drove Q4 performance.
3. Revenue Quality
Revenue quality at Ollie’s is high due to its counter-cyclical nature and the stabilizing influence of its consumables segment.
Predictability and Stability
While individual store inventory is unpredictable (the “treasure hunt”), total corporate revenue is remarkably stable. Net sales grew from $2.27 billion in FY2024 to $2.65 billion in FY2025, a 16.6% increase.
This growth trajectory is supported by the high percentage of consumables (36.2%), which act as a recurring revenue stream.
Customers visit for the “needs” (detergent, snacks) and stay for the “wants” (electronics, home decor).
Concentration Risk and Demographic Insulation
Ollie’s faces negligible customer concentration risk, as its revenue is spread across millions of individual consumers. On the supply side, however, there is a theoretical “vendor concentration” risk. While the company sources from 1,200+ suppliers, it maintains particularly deep relationships with its top 15 vendors, some lasting for over 15 years.
If several of these major manufacturers were to change their liquidation strategies simultaneously, it could impact on the quality of the “treasure hunt” inventory.
Cyclicality and Macro-Sensitivity
Ollie’s is a primary beneficiary of the “trade-down” effect. During periods of high inflation or economic uncertainty, middle-income consumers migrate from department stores and traditional grocers to extreme-value retailers.
Inflationary Tailwinds: Rising costs at traditional retailers widen the “price gap,” making Ollie’s value proposition more compelling.
Deflationary/Stable Risks: In a period of aggressive discounting by big-box retailers, Ollie’s relative value might diminish, though its 20-70% discount threshold remains a significant buffer.
4. Cost Structure
Ollie’s cost structure is optimized for high-volume, low-complexity retail. The company maintains a lean operating model that prioritizes merchandise margins and supply chain efficiency.
Key Cost Drivers
Cost of Goods Sold (COGS): COGS includes the purchase price of merchandise, inbound freight, and the costs associated with the distribution center network. In FY2024, cost of sales was 60.4% of net sales, a decrease from 64.1% in FY2022, primarily driven by favorable supply chain costs and high-margin deal acquisitions.
Store Labor and SG&A: Selling, General, and Administrative (SG&A) expenses were 26.8% of sales in FY2024. This includes store-level labor, which has seen some upward pressure due to wage inflation, and corporate overhead.
Logistics and Distribution: The company operates a hub-and-spoke distribution model. Distribution center depreciation is included in COGS, while outward freight to stores is part of the operational expense base.
Pre-opening Expenses: As an aggressive grower, pre-opening costs are a persistent line item. These include “dark rent” (rent paid before a store opens), hiring, and training. In Q2 FY2025, pre-opening expenses rose to $9.0 million due to the accelerated opening schedule of former Big Lots and 99 Cents Only locations.
Margin Analysis and Operating Leverage
Ollie’s exhibits significant operating leverage. As comparable store sales increase, fixed costs like rent and depreciation are leveraged, driving higher operating margins.
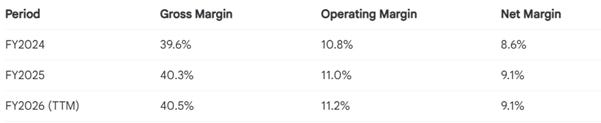
The company’s ability to maintain a gross margin above 40% in a competitive retail environment is evidence of its procurement edge. While traditional retailers struggle with “shrink” (theft) and promotional markdowns, Ollie’s “treasure hunt” model naturally minimizes markdowns - if an item doesn’t sell, it is simply moved to a more aggressive clearance rack, but the initial “buy” was so cheap that the margin remains protected.
5. Capital Intensity
Ollie’s business model is capital-intensive due to its reliance on physical stores and large inventory holdings, but it generates sufficient cash to fund this growth internally.
Asset Requirements and CapEx Trajectory
The company must invest heavily in new store build-outs and distribution capacity to maintain its growth algorithm.
Capital Expenditures: CapEx has escalated significantly, from $51.7 million in FY2022 to over $124 million in FY2024.For FY2026, the guidance is $103 million to $113 million.
Distribution Centers: To support 1,300+ stores, Ollie’s must periodically build or expand massive distribution hubs. These are large capital outlays that precede revenue generation from the stores they serve.
Working Capital and Cash Conversion Cycle (CCC)
Inventory Dynamics (The “Buy-Ahead” Strategy)
Inventory is the largest component of Ollie’s working capital. Unlike Walmart or Target, which use sophisticated replenishment algorithms to minimize stock, Ollie’s purposefully builds inventory to secure deep-value closeouts. For instance, in FY2025, Ollie’s increased its inventory by 5.3% to $531 million to support accelerated store openings and “mega-deals” in the toy and seasonal categories.
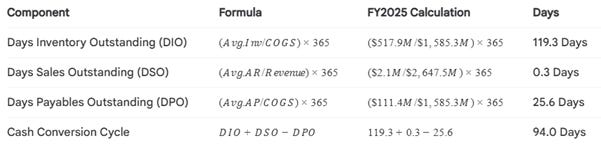
Detailed CCC Calculation
The CCC measures how many days it takes for a dollar spent on inventory to return as a dollar of sales.
Analytical Interpretation of the Working Capital Model
DIO (119.3 Days): This is exceptionally high for retail (industry average is often <60 days). However, for Ollie’s, a high DIO is a strategic asset, not a liability. It represents “stored value” - brand-name goods purchased at 70% off that will be sold at 40% gross margins. The reduction from the 146 days seen in FY2022 reflects improved supply chain throughput and faster turnover in the “Consumables” segment.
DSO (0.3 Days): Ollie’s is a pure-play cash/credit retail business with no wholesale or trade receivables. Cash is captured at the point of sale, providing immediate liquidity.
DPO (25.6 Days): Ollie’s pays its vendors quickly. In the liquidation market, speed of payment is a competitive advantage. Being able to wire cash immediately to a manufacturer in distress allows Ollie’s to secure the “First Call” for the best deals.
Net Working Capital: As of Q1 FY2026, the company maintained a healthy current ratio of 2.1x, with $531 million in inventory and $236 million in cash. This liquidity allows the company to fund its $100M+ annual CapEx entirely through internal cash flow.
Summary of Capital Efficiency
Ollie’s operates with a negative cash gap relative to JIT retailers, meaning it must pre-fund its inventory. However, the ROIC of 10.77% - which is nearly double the retail defensive median - demonstrates that the company is highly effective at turning this “trapped” inventory capital into outsized profits.
6. Growth Drivers
Ollie’s growth is not merely a function of market expansion but of strategic positioning within the decaying traditional retail landscape.
Primary Growth Levers
The “1,300 Store” Algorithm: Management has consistently identified a domestic opportunity for at least 1,300 stores, more than double the current count of 672. This is the primary structural tailwind.
Second-Generation Real Estate: By moving into boxes vacated by retailers like Bed Bath & Beyond, Big Lots, and Kmart, Ollie’s reduces its CapEx per store and secures established retail locations with existing traffic patterns.
Ollie’s Army Scaling: Growing the loyalty program (currently 17.5M members) increases the predictability of revenue. Members spend 40% more per trip, so converting a “casual” shopper into an “Army” member is a high-ROI activity.
Category Expansion: The company is actively refining “under-productive” categories. For example, recent shifts in the seasonal and toy categories led to outsized performance in the fourth quarter.
Structural vs. Cyclical Dynamics
Structural Tailwind: The ongoing “retail apocalypse” among mid-tier department stores provides a perpetual supply of both discounted inventory and low-cost real estate.
Cyclical Tailwind: Inflation-driven trade-down behavior. While this may fluctuate, the structural decline of competitors like Big Lots provides a more durable growth path.
The Single Biggest Constraint: Procurement Talent
The primary constraint on growth is not capital or real estate, but the merchant team. The ability to find, negotiate, and execute closeout deals is a specialized skill. If Ollie’s cannot scale its team of expert buyers at the same rate it scales its store count, the quality of the “treasure hunt” inventory could dilute, leading to lower comp sales and margin erosion.
7. Competitive Moat
Ollie’s possesses a “narrow-to-wide” moat that is primarily based on cost advantages and an intangible “sourcing network.”
Sources of Economic Protection
The “First Call” Advantage: Because Ollie’s can buy $50 million of inventory in a single transaction and clear it out of a manufacturer’s warehouse in days, it is the “first call” for major brands like P&G or Mattel when they have a problem.This is a massive barrier to entry for smaller players.
Logistics of the “Unstructured”: Traditional retailers (Walmart, Amazon) are built for structured, predictable supply chains. They struggle to integrate 50,000 units of a “one-time” item into their systems. Ollie’s entire infrastructure is built to handle the chaotic, non-replenishable nature of closeouts.
Proprietary Data (Ollie’s Army): With 80% of sales linked to a loyalty ID, Ollie’s knows exactly who its customers are and what they buy, allowing for highly targeted flyer distribution and marketing spend optimization.
Evidence of Moat Durability: ROIC vs. WACC
A company creates value when its Return on Invested Capital (ROIC) exceeds its Weighted Average Cost of Capital (WACC).
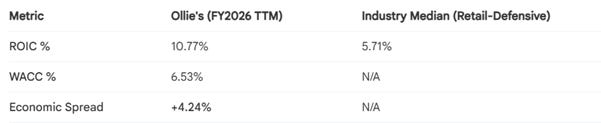
Ollie’s generates returns nearly double the industry median and comfortably above its cost of capital. This spread is the ultimate quantitative proof of a moat.
Moat Assessment: Widening
The moat is widening due to scale-based self-reinforcement. As Ollie’s gets bigger, it becomes more valuable to suppliers (as a larger liquidity provider) and more valuable to customers (as it can secure even larger and more diverse deals). This creates a virtuous cycle that is difficult for regional discounters to replicate.
8. “Ollie’s Army” Deep Dive
The Ollie’s Army program is perhaps the most undervalued asset on the balance sheet. Unlike traditional loyalty programs that offer vague rewards, Ollie’s Army is the primary driver of the company’s marketing and sales strategy.
Program Statistics and Impact
Membership: 17.5 million members.
Sales Contribution: Over 80% of total sales.
Basket Size: Members spend ~40% more per transaction than non-members.
Frequency: Members visit 50% more frequently than non-members (inferred from spend and sales contribution data).
Comparative Analysis: OLLI vs. Costco vs. Walmart
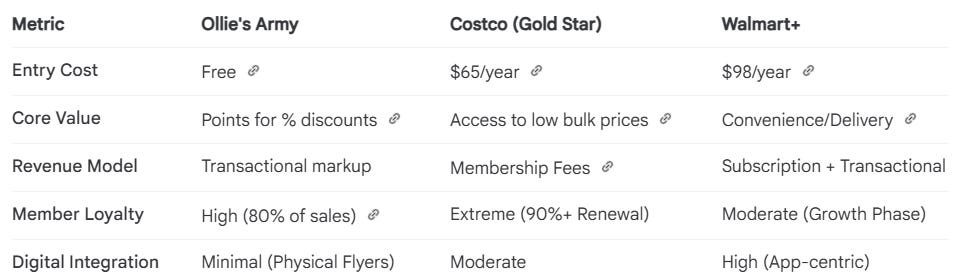
Ollie’s Army is unique because it provides “membership-level” loyalty without the friction of a membership fee. This allows Ollie’s to capture data on a much wider swath of the population than Costco, which filters for a certain income level via its fee.
Accounting and Future Strategy
The company maintains a “Loyalty Program Liability” on its balance sheet ($14.4 million as of late 2025) to account for unredeemed points.
This is a conservative accounting treatment that reflects the program’s maturity. The next step in the program’s evolution is the co-branded credit card, which is already showing “strong spending and shopping frequency,” further entrenching the brand in the consumer’s lifestyle.
Conclusion
Ollie’s Bargain Outlet is an exceptionally well-run retail specialist that has successfully industrialized the “treasure hunt.” By serving as a critical pressure-release valve for the global consumer goods supply chain, the company has carved out a high-margin, high-growth niche that is inherently resistant to the pressures of e-commerce. With a clear path to doubling its store count and a loyalty program that commands 80% of its sales, Ollie’s is positioned as a premier long-term compounder for fundamental investors. The combination of industry-leading ROIC, robust FCF generation, and a counter-cyclical revenue base makes it a unique asset in the modern retail portfolio.
Thanks for reading!
Stiliyan Loukanov, Feather Fund
Open an account with Interactive Brokers:
https://ibkr.com/referral/stiliyan756
Sign up to Revolut with the link below to support the blog:
ttps://revolut.com/referral/?referral-code=stiliyujwu!MAY1-24-AR
Open an account with eToro to support the blog:
Disclaimer: The information presented here, including ideas, opinions, views, predictions, forecasts, commentaries, or suggestions, whether explicitly stated or implied, is intended purely for informational, entertainment, or educational purposes. None of the content should be interpreted as personalized investment or financial advice. Although every effort has been made to ensure the accuracy of the information provided, errors or inaccuracies may be present. Always exercise caution and seek professional financial advice before making any investment decisions.